Ice Hockey Bet Types Explained: Moneyline to Same-Game Parlays
 Available in US
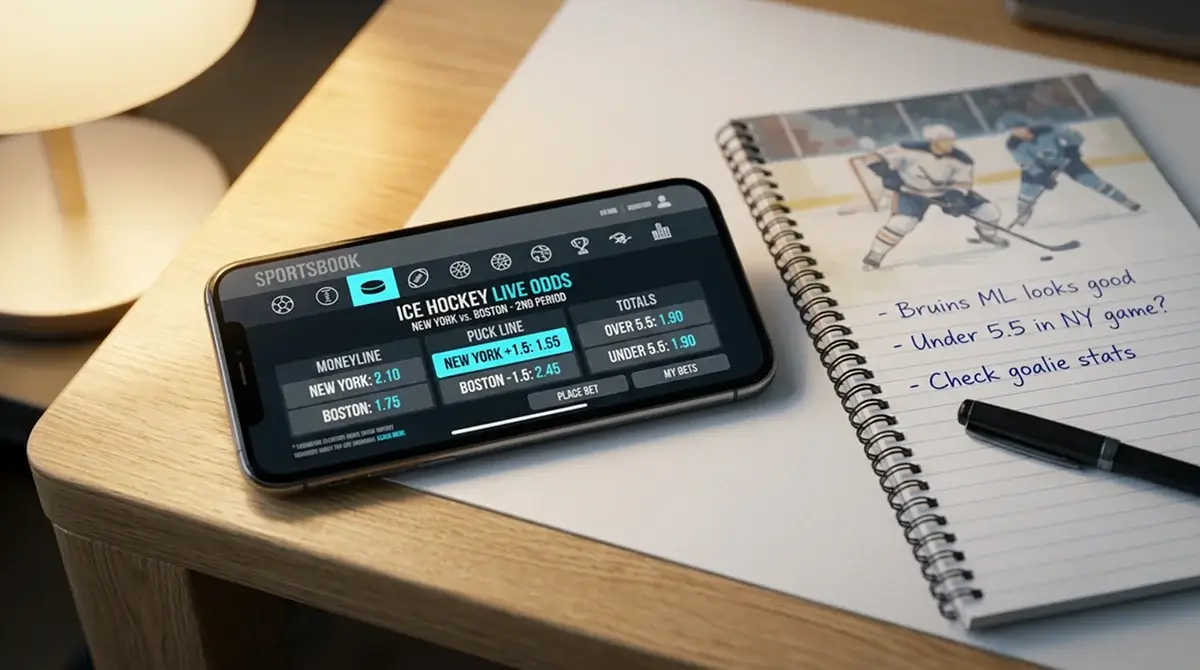
Table of Contents
- The Map of Hockey Markets Most Guides Skip Over
- The Three Anchor Markets Every Hockey Bettor Starts With
- Moneyline: Two-Way Versus Three-Way
- Puck Line: How the Hockey Spread Behaves
- Totals: Where the Reverse Favourite-Longshot Bias Lives
- Player Props: Goalscorers, Shots and Saves
- Period Markets and Time-Segment Bets
- Accumulators and Parlays
- Futures and Awards
- Specialist and Novelty Markets
- Knowing the Map Before You Pick the Route
- Common Questions UK Hockey Bettors Ask About Bet Types
The Map of Hockey Markets Most Guides Skip Over
Hockey, as the editorial team at Covers once put it, “isn’t as popular as some of the other major sports, but the edges on the ice are limitless, with a plethora of ways to get in on the action.” That sentence captures the thing about hockey betting that other guides keep getting wrong. They walk you through moneyline, puck line and totals as if those three markets were the whole picture, and then send you off to bet. The actual map is far bigger and far more interesting.
The first season I bet hockey seriously, I made the same mistake. I lived on moneyline and totals for the first three months and then realised, somewhere around mid-November, that half the value I had been ignoring sat in 60-minute betting, period markets and well-priced anytime goalscorer props that the books were not always pricing as carefully as they were pricing the headline lines. The bettors who beat hockey long-term tend to be the ones who know which market to bet, not just which side to take.
This guide walks through every meaningful ice hockey market a UK punter is likely to encounter at a UKGC-licensed sportsbook, with worked examples and the practical context that determines which markets are worth your stake on a given night. I have spent nine years tracking these prices across both NHL and EIHL, and the patterns I will describe are the ones I check before placing any meaningful bet.
The Three Anchor Markets Every Hockey Bettor Starts With
If I had to bet using only three markets for the rest of my career, I would pick moneyline, puck line and totals. They are the anchor of every hockey betting card at every UK book, and the prices on every other hockey market are derived from them. Understanding how they relate to each other is the most important piece of knowledge in hockey betting, and most beginner guides treat them as three separate things rather than as three views of the same underlying probability.
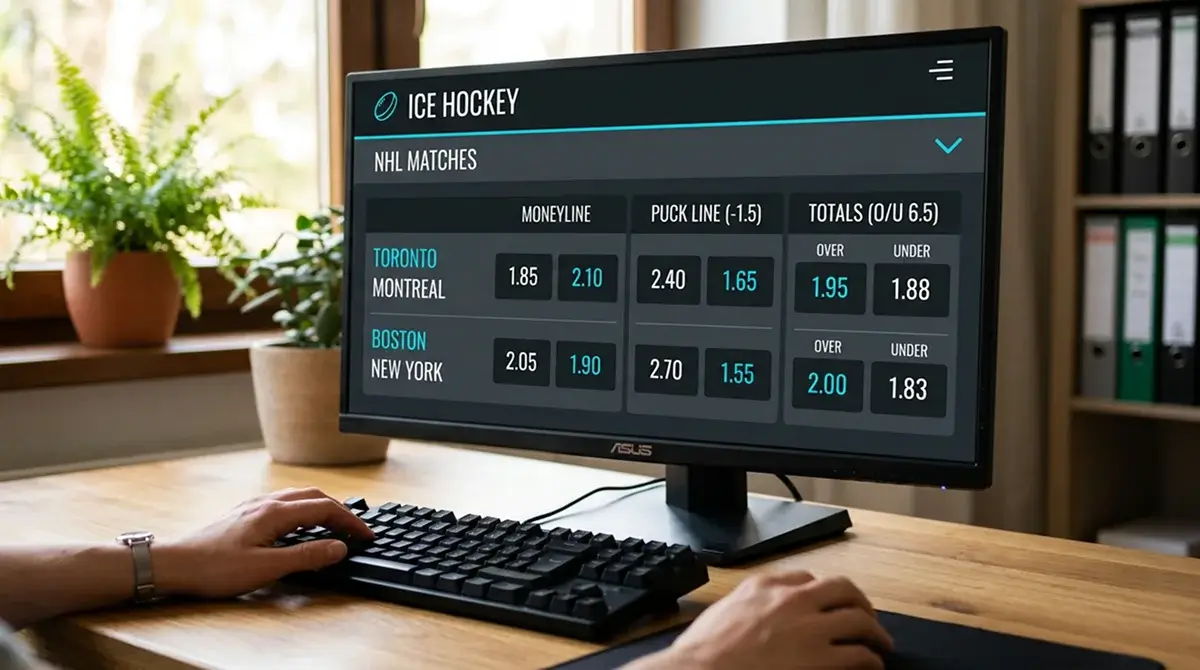
The moneyline is the simplest form: pick the winner of the match. The two-way moneyline includes overtime and shootout, so a regulation-time tie that is decided in extras counts for the winning side. UK books quote it in decimal odds by default — Edmonton at 1.65 to win, Vancouver at 2.30. If you convert that to implied probability (one divided by the decimal odds), Edmonton is implied at 60.6 per cent and Vancouver at 43.5 per cent. The two together add up to 104.1 per cent, with the four per cent above 100 being the book’s hold.
The puck line is the hockey spread, almost universally fixed at 1.5 goals. The favourite gives 1.5 goals at longer odds; the underdog gets 1.5 goals at shorter odds. If you take Edmonton -1.5 at 2.20, they need to win by two or more goals for the bet to win. If you take Vancouver +1.5 at 1.70, they need to either win outright or lose by exactly one goal. The puck line is structurally interesting because it captures the moneyline favourite’s most likely losing path — the one-goal loss — and the moneyline underdog’s most likely winning path — the regulation tie.
The total — over or under a posted combined goal count — completes the anchor triangle. The line usually sits at 5.5 or 6.0, sometimes 6.5 on big-scoring matchups. The over and under are typically priced symmetrically with the book’s hold built into both sides. A 6.0 total at 1.90/1.90 carries a 5.3 per cent hold; the same line at 1.95/1.85 carries a smaller hold on the favoured side.
The connecting thread underneath these three markets is the implied-probability calculation. Karry Shreeve of Caesars Sportsbook has noted that “most of the time I’d say that a goalie, at most, is worth three to five per cent of implied probability” — and that single observation tells you why the three anchor markets are not independent. A goaltender swap repositions the moneyline, which moves the puck-line price, which shifts the totals line. All three move together, which is why understanding all three matters even if you only ever bet one of them.
Moneyline: Two-Way Versus Three-Way
The first hockey moneyline I ever lost in dramatic fashion was a two-way Vancouver favourite that gave up a tying goal with eight seconds left in regulation, then lost in overtime. That experience taught me what UK guides rarely emphasise: the difference between two-way and three-way moneyline pricing is not academic. It directly affects how often you cash on apparently similar bets, and the prices on the two markets diverge in interesting ways.
The two-way moneyline includes overtime and shootout. Either Vancouver or Edmonton wins the match — there is no third outcome, the book is offering two priced options, and the hold is built across both. Almost all retail moneyline volume in the UK goes into this market.
The three-way moneyline — also called 60-minute betting, or regulation moneyline — prices the result at the end of three regulation periods only. There are three priced outcomes: Vancouver wins in regulation, Edmonton wins in regulation, or the game is tied after sixty minutes. Because the tie is a meaningful third outcome, the prices on either team are noticeably longer than the equivalent two-way prices. Edmonton at 1.65 on the two-way might be 2.10 on the three-way; Vancouver at 2.30 on the two-way might be 2.90 on the three-way; the tie sits at around 3.60 to 4.20 depending on the matchup.
Why does this matter? Because three-way betting protects you against a specific outcome that two-way betting punishes you for. If you have backed Edmonton at 2.10 in the three-way market and the game ends in a 3-3 tie after sixty minutes, the bet loses cleanly — but you priced the bet at longer odds, which compensates over time. If you have backed Edmonton at 1.65 on the two-way and the game goes to overtime, you are still alive for the win.
The strategic reading: backing favourites is generally better on the two-way (you get the overtime path); backing underdogs is generally better on the three-way (the price is longer for capturing the regulation win that the underdog actually plays for). Roughly twenty per cent of NHL games end in regulation ties before going to overtime, which is the structural reason three-way pricing is more generous on both sides than the two-way market.
UK books also offer the related “draw no bet” market on hockey for some games — essentially the three-way market with the tie outcome refunded as a stake-back. The price is shorter than the three-way equivalent because the protection cost is built in. For risk-averse bettors who want regulation protection without paying the full three-way price, draw no bet is a reasonable middle ground on selected games.
Puck Line: How the Hockey Spread Behaves
The puck line is the most misunderstood of the anchor markets. UK punters who come from football betting often expect the spread to behave like a Asian handicap, with variable margins reflecting the favourite’s strength. Hockey does not work that way. The puck line is fixed at 1.5 goals across virtually all NHL and most EIHL games, and the price varies rather than the margin.
Take a representative example. Edmonton are -1.5 favourites against Vancouver at 2.40, and Vancouver are +1.5 underdogs at 1.55. The implied probability of Edmonton winning by two or more goals is roughly 41 per cent. If you back Edmonton -1.5 and they win by exactly one goal, the bet loses. If you back Vancouver +1.5 and Vancouver lose by one goal, the bet wins.
The structural reason puck-line pricing produces consistent value pockets is the role of the empty-net goal. NHL teams routinely pull their goaltender for an extra attacker when trailing by one goal in the final two minutes of regulation. That tactic produces one of two outcomes: either the trailing team scores and ties the game (which kills the favourite’s puck-line bet by sending the game to overtime where it can only go on the two-way), or the leading team scores into an empty net and wins by two goals (which cashes the puck-line favourite). Roughly thirty to forty per cent of one-goal NHL games end up resolved by empty-net scoring in the final ninety seconds, which is a meaningful chunk of puck-line outcomes.
The strategic reading: backing favourites on the puck line is essentially a bet that the empty-net goal will arrive. Backing underdogs on the puck line is essentially a bet that the game stays close enough to one goal that no empty-net swing materialises. Knowing which teams play tight defensively in the final two minutes — and which teams pull the goalie earlier in the late stages — matters more for puck-line outcomes than for any other market.
For UK bettors, an additional wrinkle is alternate puck lines. Some books offer alternate spreads of 2.5 or 3.5 goals at longer odds, and these can produce value on heavy favourites against weak underdogs. The deeper mechanics of the puck line — pricing windows, alternate spreads, empty-net dynamics and worked examples for UK punters — sit in our guide to puck line betting explained.
Totals: Where the Reverse Favourite-Longshot Bias Lives
Totals look like the simplest market in hockey. You pick over or under a posted goal count, and the bet settles at the final whistle including overtime. What makes totals interesting is a structural pricing inefficiency that has been documented in the academic literature for over thirty years.
The Woodland market efficiency studies on hockey and baseball found a consistent reverse favourite-longshot bias in totals markets: bets on the underdog outcome (the “under” in lower-scoring sports, the “over” in higher-scoring sports) systematically returned higher than market-efficiency hypotheses predicted, and the bias persisted across decades of data. For NHL totals specifically, the under has historically performed better than its closing-line price would suggest, particularly on games where the posted total is above the league average.
The strategic reading is nuanced. The under bias does not mean every under is a value bet. It means that totals priced at the higher end of the typical range — 6.5 and above in NHL terms — tend to deliver under outcomes more often than the prices imply. The under bias also tends to be stronger on games involving defensive-minded teams and weaker on games between two top-five offences.
UK books typically post NHL totals at 5.5 or 6.0 as default, moving to 6.5 only on games between two high-scoring sides. The juice is usually symmetric (both over and under at 1.90 to 1.95) but can swing to one side on heavily public games where casual money lands disproportionately on the over. Watching the line movement on totals is a useful auxiliary signal — totals that drift down through the day after opening at 6.0 are signalling sharp money on the under.
Team totals are a derivative of the main total. Edmonton over 3.5 at 2.10 is a bet on whether Edmonton specifically will score four or more goals, regardless of what Vancouver does. Team totals are useful on games where you have a strong directional view on one side but are unsure about the other side’s contribution to the combined total. Period totals — over or under 1.5 in any given period — are another derivative, popular in live betting where the game is unfolding in front of you.
Player Props: Goalscorers, Shots and Saves
The first time I cashed a meaningful anytime goalscorer prop, I was watching Connor McDavid against Calgary at four in the morning UK time and had backed him at 1.85 to score in regulation. He scored on his second shift. Player props are the entry point to a different category of hockey betting where the variance is higher, the prices are more idiosyncratic, and the line shopping potential is the highest of any market category.
Anytime goalscorer is the headline player prop. You back a specific player to score at least one goal in regulation (or in some books, the full game including overtime). Prices vary enormously across players — top-line forwards at 1.80 to 2.20, second-line forwards at 2.40 to 3.00, defenders at 4.00 to 8.00, fourth-line forwards at 6.00 to 10.00. The variance between two UK books on the same anytime goalscorer is often the largest on the entire hockey card, sometimes twenty per cent or more on a mid-tier player.
Shots on goal props (over or under a specific number for a named player) are the most analytically tractable prop in hockey. Shot volume stabilises across a season faster than goal-scoring does, which means the books price these markets fairly cleanly for elite forwards and slightly less cleanly for second-line and defender props. A player who averages 3.2 shots per game over a full season is unlikely to drop to 2.5 across a meaningful sample, which makes the over 2.5 line a more reliable bet than its surface price suggests on a player with a stable shot-volume profile.
Goaltender saves props price the number of saves a starter will make. They are essentially a leveraged combination of shots faced and save percentage. A goalie facing a top-five shot-volume offence is going to face thirty or more shots most nights, which puts the saves line at 28.5 or 29.5 typically. A goalie facing a bottom-five offence might see the line at 23.5 or 24.5. Saves props are the prop most affected by the totals line — a lower expected total often comes with a lower expected shots-against, and the saves line shifts accordingly.
The line shopping rule applies more strongly to player props than to any other hockey market. Always compare at least two UK books before placing a prop bet of any size. The differences add up over a season more than most bettors realise.
Period Markets and Time-Segment Bets
Period markets divide the game into its three twenty-minute building blocks and price the outcome of each independently. They are useful for two specific situations: in-game betting where the game is unfolding and you have a directional view, and pre-match betting where you want exposure to a specific game state rather than the full result.
First-period winner is the most popular of the period markets. It is a three-way bet (home wins the first period, away wins the first period, or first period is tied). Prices are typically generous compared to the full-game moneyline because period results are higher-variance than game results. A team that wins games at 1.65 might win first periods at 2.30, with the tie at 2.50. Similarly for second period and third period markets.
Period totals — over or under 1.5 goals in a specific period, sometimes 0.5 — give you a way to bet directional scoring without committing to a full-game totals view. First-period totals are interesting because the data is the most stable across the league: first-period scoring averages remain fairly consistent through the season, which means the line tends to settle quickly.
Race-to-X markets are the period family’s most novelty-friendly entry. Race to three goals (which team scores the third goal first) is the most common version. The price is driven by team scoring rates rather than head-to-head expectation, which makes these markets interesting on high-scoring favourites against low-scoring underdogs.
Time-segment bets cover specific game minutes — first goal scored in 0-5 minutes, 5-10 minutes, and so on. These markets are typically posted only on flagship games and carry wider juice than the period markets. They are useful for in-game betting where the game has settled into a specific pattern, but they are not usually a sustainable pre-match betting source.
Accumulators and Parlays
UK accumulator culture is strong on football, and naturally bettors carry the habit into hockey. Hockey accumulators work the same way mechanically — you combine multiple bets into a single ticket where every leg must win — but the relationship to expected value is more punishing than football accumulators because the per-game variance is higher in hockey.
The maths is straightforward. A two-leg moneyline accumulator on two favourites at 1.65 each pays 2.72 if both legs win, against a true probability of 36.7 per cent if both legs are independent. The book hold on a two-leg combination is essentially the product of the individual holds, which means the eight per cent edge on each single leg becomes a sixteen per cent edge across the accumulator. The maths gets worse as you add legs.
Same-game parlays (SGP) are the modern variant of the accumulator. Instead of combining bets across multiple games, you combine multiple markets within a single game. SGPs are priced with a correlation adjustment — the book recognises that certain legs are not independent (a team winning is correlated with a top forward on that team scoring) and adjusts the combined price accordingly. The adjustment is usually unfavourable to the bettor, but the size of the adjustment varies between books in ways that occasionally produce genuine value.
The in-play volume picture is worth knowing about. In-play (live) hockey betting accounts for over sixty per cent of total hockey wagering volume at the major books, and accumulator-style bets are part of that ecosystem. Across all sports betting in regulated US markets, the 2025 calendar year alone produced $165.58 billion in total handle with a 10.15 per cent average hold for the books — a single data point that captures how much accumulator and live volume drives sportsbook profit. UK numbers are smaller but follow the same shape.
The strategic guidance on accumulators is the same I have given for nine years: small stakes, fewer legs, and only when the correlation works in your favour. A two-leg SGP combining a side moneyline with a top-line forward to score is fundamentally a different bet from a four-leg cross-game accumulator on randomly chosen favourites. The first can occasionally show value; the second almost never does over a meaningful sample.
Futures and Awards
Futures markets cover season-long outcomes — Stanley Cup winner, conference winners, division winners, individual awards. They are slower-moving than match markets and carry their own structural quirks worth knowing about.
The Stanley Cup outright is the headline futures market. The 2025-26 board opened with Colorado Avalanche at +135 and Carolina Hurricanes at +165 as the top of the chalk. Those prices reflect a combination of last season’s playoff results, summer roster moves, and forward-looking projections for the upcoming year. Cup futures behave differently from moneyline markets because the time horizon stretches across the full season — prices drift based on injuries, trades, hot streaks and slumps, and the book is constantly re-pricing rather than settling a single market.
Conference and division winners are derivative outright markets. The Eastern Conference and Western Conference winners are the two playoff bracket finalists; the four division winners are the regular-season seedings. Conference winner markets tend to be more volatile than Cup futures because they resolve in May rather than June, which means the seasonal news cycle has slightly less time to affect them.
Award futures cover the major individual trophies. Hart Trophy (regular season MVP), Vezina (best goaltender as voted by GMs), Norris (best defender), Calder (best rookie), Selke (best defensive forward), and the Maurice Richard (most goals). Award markets carry an additional layer of narrative pricing — Hart and Vezina in particular respond to media coverage and storyline momentum in ways that pure performance metrics do not. The Conn Smythe (playoff MVP) only matters once the playoffs begin, and its market opens correspondingly later.
Strategic reading on futures: the value windows tend to be late October (when the books reposition after the first three weeks of regular-season data), late December (between Christmas and New Year, when the books refresh prices ahead of the second half), and the week after the trade deadline (when rosters have moved and the books need to repost). Pre-season prices rarely offer the best entry point.
Specialist and Novelty Markets
Beyond the standard markets, UK books offer a tail of specialist and novelty markets that get attention from casual bettors and occasionally from sharp ones too. They are worth knowing about because they form part of the betting landscape, but they are also worth understanding as a category that mostly favours the books.
First goalscorer is a popular novelty market. You back a named player to score the first goal of the game. The prices are driven by team scoring rate, player line position and ice-time projections, and they are typically wider in juice than anytime goalscorer markets because the first-goal outcome is harder to predict than the any-time outcome.
Method of victory markets price how a side wins — regulation, overtime or shootout. These are essentially three-way moneylines with an additional sub-outcome layer, and they are most interesting on games where you have a strong view on the game state rather than just the winner.
Multi-game accumulator boost markets offer enhanced prices on combinations the book has selected — usually three or four favourites on a given night. The boost can be genuine, particularly when the book is using it as a promotion to attract volume on a flagship night, but more often the headline boost is more than offset by the underlying juice on the combined legs.
Live-only specialist markets — next goalscorer in this period, race to next goal, will there be a penalty in the next three minutes — populate the in-play menu in the bigger books. They are not generally a sustainable edge source because the book re-prices them in real time as the game state changes, but they can be useful for hedging or for taking a directional view on a specific moment in the game.
Knowing the Map Before You Pick the Route
The bettors I know who have profited from hockey over multi-year stretches tend to share one habit: they do not bet every market on every game. They pick the market that matches what they actually know about a specific matchup and ignore the rest. If your edge is in goaltender analysis, you bet moneylines on goalie-driven games. If your edge is in shot-quality models, you bet totals on matchups where the shot-quality differential is large. If your edge is in line-shopping discipline, you bet anytime goalscorer props across two or three books on every meaningful game. The map of hockey markets is large enough that no single bettor needs to bet all of it. Pick the routes that match what you know, and let the rest of the map sit there for someone else.
Common Questions UK Hockey Bettors Ask About Bet Types
The bet-type questions I hear most often from UK punters cluster around the same handful of mechanical and pricing issues. The answers are worth nailing down before you stake on anything beyond moneyline and totals.
What is ‘draw no bet’ in three-way hockey markets, and when does it offer value?
Draw no bet is a three-way moneyline variant where a regulation tie returns your stake rather than settling as a loss. The price is shorter than the three-way market because the tie protection is built into the odds. It offers value when the regulation tie probability is genuinely material (typically twenty per cent or more) and when the book’s draw no bet pricing has been set wider than the implied tie-stake-return figure. On flagship games with strong defensive sides on both lines, draw no bet on the favourite can be a more sensible bet than the standard two-way moneyline.
Why are anytime goalscorer prices so different across UK sportsbooks?
Anytime goalscorer pricing combines team-level scoring expectations, player ice-time projections, line-position assumptions and goaltender opponent expectations. Different books weight these inputs differently, and the resulting prices can vary by twenty per cent or more on mid-tier players. The variance is largest on second-line and defender props, where the underlying model assumptions matter more than they do on a top-line forward whose scoring rate is more predictable. The practical takeaway is that line shopping matters more on anytime goalscorer than on any other hockey market.
How do period-winner markets price intermission momentum?
The books price each period as a relatively independent event with adjustments for game state at the start of the period. A team trailing 3-0 after the first period is more likely to win the second period than its season-long numbers suggest, because the trailing team plays more aggressively and the leading team can drift into a defensive shell. The books price this momentum adjustment into second and third period markets, which tends to flatten the prices compared with first-period markets where game state is irrelevant.
Are same-game parlays priced as a simple product of legs or with adjusted correlation?
Same-game parlays are priced with a correlation adjustment rather than as a simple product. The book recognises that within a single game, certain outcomes are positively or negatively correlated — a team winning is positively correlated with its top forwards scoring, for instance — and adjusts the price accordingly. The adjustment is typically unfavourable to the bettor because the book builds a margin into the correlation calculation. Some books are more punitive than others, and the size of the adjustment varies enough that occasional SGP value does exist for bettors who shop the same combination across two or three books.
Prepared by the ice Hockey Betting editorial staff.