Value Betting in the NHL: Finding Edges
 Available in US
The only kind of betting that compounds
Most NHL punters do not lose because they pick the wrong teams. They lose because they pay too much for the right ones. The price you get on a bet, relative to the true probability of the outcome, determines whether the bet is profitable over a long sample — and most casual punters never check that relationship. They see a team they like at any price and bet. The book takes its hold and the punter takes their loss.
Value betting is the discipline of only placing bets where the price genuinely exceeds the true probability. Kyle Kargel at StatsAlt summed up the right mindset: “Winning in hockey requires more than just knowing who’s hot or who won their last game. The NHL is a high-variance league where small edges, timing, and context often matter more than raw talent.” Value betting takes that variance seriously. It accepts that any single bet might lose regardless of how well-priced it was, but it requires every bet to clear a fair-price threshold before it gets placed.
This guide covers what value actually means in the no-vig sense, how to combine your own model with the market, where niche markets offer the best pockets of value, staking discipline against edge size, and the trap of treating promotional boosts as genuine value sources.
Defining value and the no-vig fair price
The technical definition of a value bet is straightforward: a bet where the true probability of winning is higher than the implied probability of the price. In decimal terms, a 2.50 ticket has an implied probability of 40%. If your honest estimate of the true probability is 45%, you have a value bet — the price is too long for the actual probability of the outcome.
The complication is that the quoted price includes the book’s juice. A typical NHL 2-way moneyline quotes both sides at prices that sum to roughly 104-105% of implied probability — the extra 4-5% is the book’s hold. To find the no-vig fair price, you strip the hold out: divide each side’s implied probability by the total, and you get the book’s actual estimate of each side’s true probability.
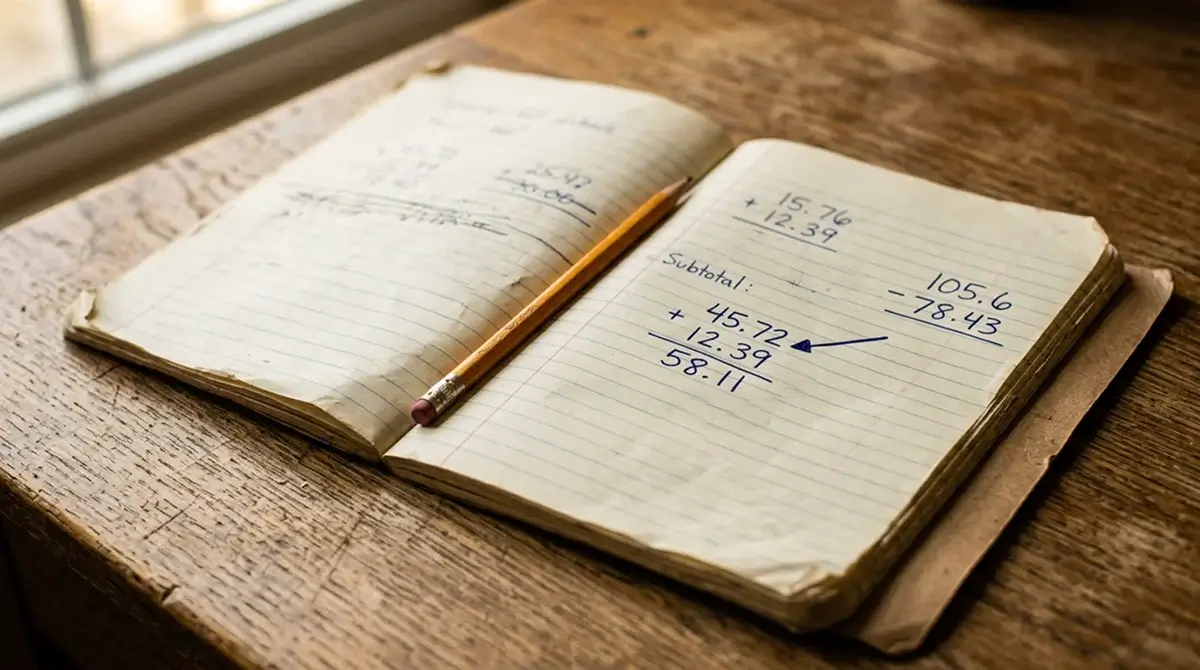
A line of 1.83 favourite versus 2.10 underdog has implied probabilities of 54.6% and 47.6%, summing to 102.2%. Dividing each by 102.2% gives no-vig fair probabilities of 53.4% and 46.6%. The no-vig favourite price is 1.87; the no-vig underdog price is 2.15. Value exists when your own estimate beats the no-vig fair price, not just when it beats the quoted price.
Building a model alongside the market
The most reliable approach to finding NHL value is to build a model whose outputs you cross-check against the market — rather than treating either as definitive on its own. A pure model-driven approach ignores information the market has that you do not; a pure market-following approach gives up any edge you might have through original research.
The right framing: your model produces a probability estimate, the no-vig fair price tells you the market’s estimate, and meaningful disagreement is the signal. If your model says 50% and the no-vig fair price implies 47%, you have a 3% edge — small but real. If your model says 50% and the no-vig fair price implies 52%, you should question your model rather than the market, because the market integrates information you may not have.
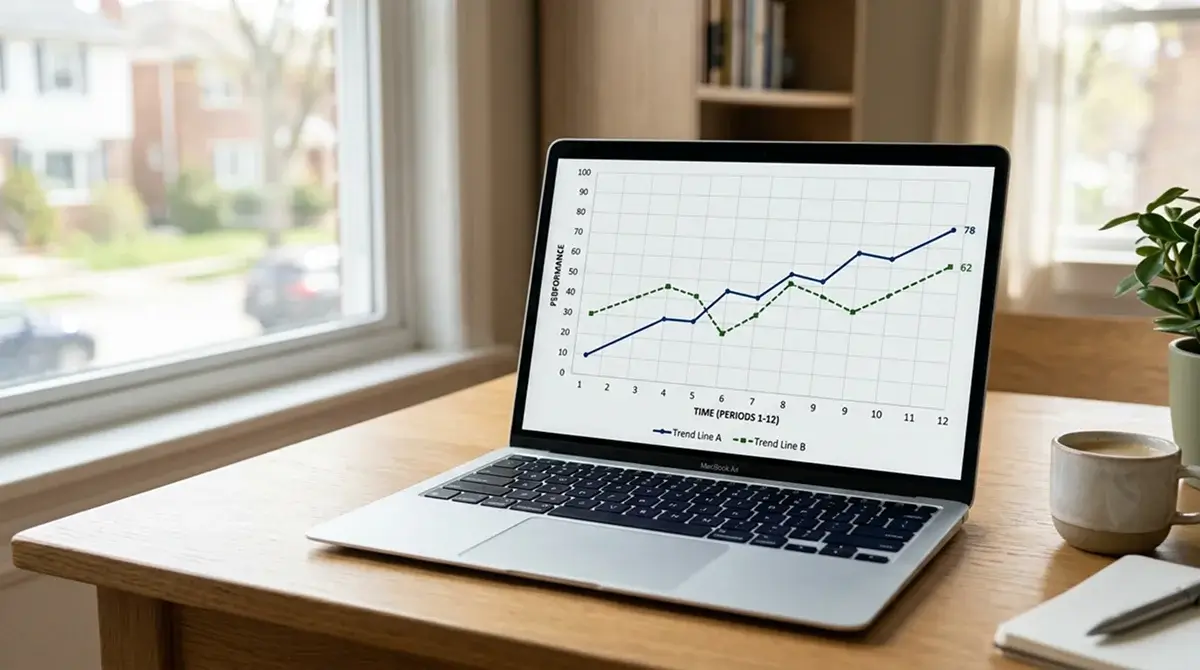
The Woodland and Woodland academic work on hockey totals — showing a reverse favourite-longshot bias where under-bets outperform their closing implied probability — is one of the cleanest examples of an edge that survives across long samples. The mechanism is consistent: public bias toward overs creates persistent pricing inefficiency that the books cannot fully arbitrage. A model that captures the under-bias on the right matchups produces small edges across many games, which compound into meaningful long-term returns.
Niche market value pockets
Headline markets — moneyline, puck line, full-game totals — are sharp on most NHL games. The juice is tight, the public volume is heavy, and books invest significant resources in pricing accurately. Niche markets are different. Period totals, team totals, specific player props on second-line skaters, and obscure prop categories carry wider juice but also wider pricing inefficiency.
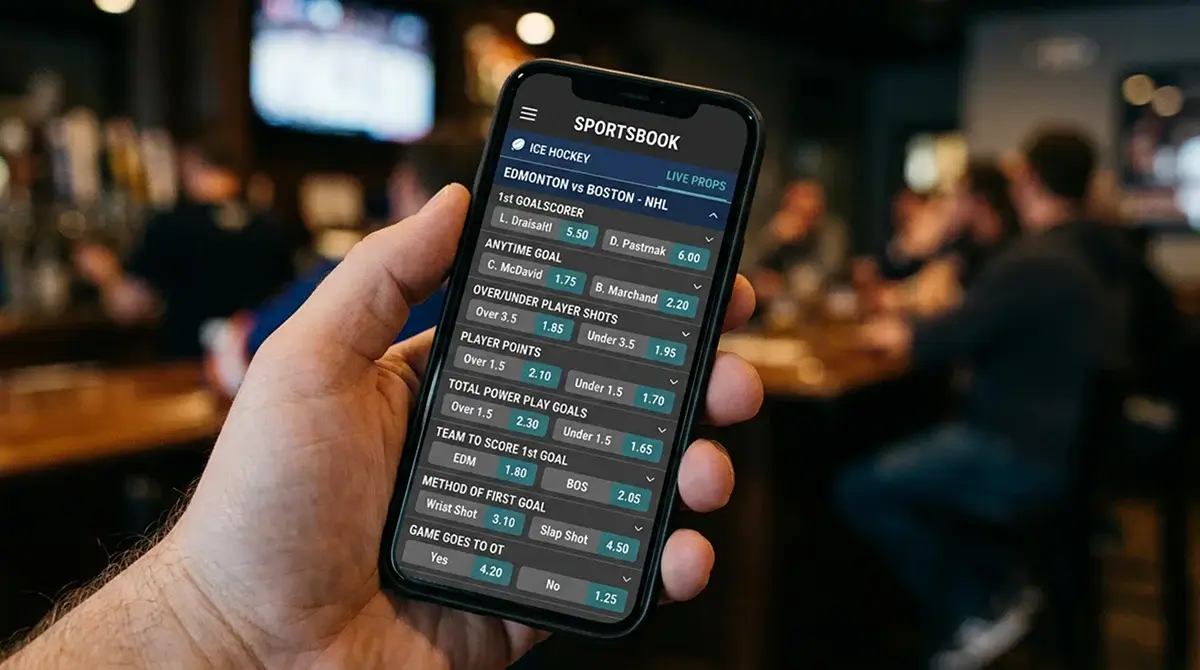
The wider hold is the cost of admission, but the inefficiency can exceed it. A first-period total at 1.5 might carry a 10% combined hold, compared to 4-5% on full-game totals. If the book’s first-period projection is genuinely off by 0.2 goals, that 10% hold still leaves room for a 5-8% edge if your model is right. The same misprice on a full-game total leaves less room because the hold itself eats most of the variance.
The trade-off is volume. Niche markets cap stakes lower and offer less liquidity. A punter relying on niche markets cannot deploy large bankroll — the books will move limits quickly on accounts that consistently beat closing prices. But for punters with modest stake sizes and the patience to work narrow markets, niche pricing is where the real edges live.
Staking against edge size
The size of any value bet should reflect the size of the edge — not the size of the punter’s enthusiasm. A 1% edge does not warrant a 5% bankroll stake. A 5% edge does. The Kelly criterion formalises this: optimal stake is proportional to edge divided by variance, with fractional Kelly (typically half or quarter) used to manage drawdown risk.
The practical version for UK punters who do not want to run formal Kelly calculations: set unit size at 1% of bankroll for typical value bets, scale up to 2% for higher-confidence edges, and refuse to scale beyond 3% even on what feels like an obvious value pick. The discipline matters more than the math — punters who scale stakes based on emotion rather than edge magnitude destroy their bankrolls through one or two oversized losses.
Volume matters too. With more than 60% of US sports betting handle now flowing through live in-play markets, the temptation to add live bets to a pre-match value strategy is strong. The discipline is to keep value betting and entertainment betting in separate bankroll buckets — live betting at full pre-match stake size compounds losses faster than almost any other pattern I have seen in punter logs. For the broader bankroll discipline framework, see the bankroll management guide.
Value against promotional boosts
UK sportsbooks aggressively promote price boosts as customer benefits. The marketing positions them as gift-equivalent value: “we have enhanced this price for you.” The reality is more complicated. A boosted price needs to be evaluated against the no-vig fair price like any other bet, not against the unboosted price. A 25% boost on a heavily juiced pre-built parlay does not necessarily produce value; it produces a less unprofitable bet.
The cleanest boost evaluation: identify the no-vig fair price for the same combination as a standalone bet, then compare the boosted price against that fair value. If the boost produces a price longer than the no-vig fair, you have genuine value. If it produces a price shorter than fair, the boost is a managed promotion designed to reduce your loss rate without making you profitable.
Many boost promotions are also restricted by maximum stake — typically 5 or 10 quid. Even if the boost does produce real value, the stake limit caps the actual edge captured. A 5% edge on a 5-pound stake produces 25p of expected value per bet. Useful, but not life-changing.
The patience of edge hunting
Value betting requires patience. The edges are small, the variance is high, and the difference between a winning and losing month is mostly noise rather than skill. The punter who insists on placing 20 bets a night to feel busy will overpay for marginal-value matchups and lose to juice over time. The punter who places 3-5 carefully chosen bets a night across well-researched markets builds the kind of slow, steady edge that compounds.
The single discipline that separates value bettors from action bettors: walking away when no value is available. Some nights the NHL board offers no genuine value — every matchup is sharply priced, every prop is juiced, every prop boost is a managed promotion. The right response is to place no bets that night, even though the matches are still being played. Forcing action when value is absent is the fastest way to lose money in any betting market, and NHL is no exception.
How many bets does a UK NHL value-hunter need before edge becomes provable?
Statistical confidence that an edge is real, rather than variance, typically requires 500-1,000 bets at minimum. Below that sample size, even a genuine 3-5% edge can look like a losing record purely due to short-run variance. Closing line value is a useful intermediate proxy — positive CLV across 100-200 bets is reasonably strong evidence of a real edge, even before the raw win-rate has stabilised.
Are promotional boosts a real value source or a customer-segmentation tool?
Mostly the latter. Boosts on pre-built parlays typically reduce the effective hold from 18-22% to 5-10% — better than the unboosted version, but rarely into genuine positive territory. Some standalone boosts on individual markets do produce real value, particularly when the underlying market was already priced tight and the boost pushes it past the no-vig fair price. The honest evaluation is to compare the boosted price to the no-vig fair price rather than to the unboosted price.
Does an NHL +EV bet need to beat closing line value to count as profitable long-term?
Closing line value correlates strongly with long-term profitability, so a +EV bet that fails to achieve positive CLV is statistically suspect. Either your model was wrong about the bet being +EV in the first place, or the market integrated information you did not have between your entry and the close. Consistent positive CLV across hundreds of bets is the cleanest evidence of a real edge; positive +EV models that produce negative CLV usually do not survive longer samples.
Written by the editors at ice Hockey Betting.